Two people at a table reviewing tax documents with a calculator and a pen

Retirement tax planning

Retirement tax planning for households with $2 million to $5 million saved, without an AUM fee.

Roth conversions, required distributions, Medicare premiums, capital gains and Social Security are one problem, not six. Flames Financial Planning coordinates them under a flat quarterly membership and, for eligible Premier members, has the return the plan produces prepared and filed through an independent tax partner.

$1,650/qtrFlames Premier: tax projections, conversion modeling, income implementation and eligible return filing.
0% AUMThe fee is a flat quarterly amount, not a percentage of what you have saved.
Seven decisionsConversions, Medicare tiers, required distributions, withdrawal order, asset location, gains, Social Security.
Minnetonka-basedA Minnesota firm working with households virtually, nationwide where permitted.

Direct answer

What Does Retirement Tax Planning Actually Cover?

The decisions that set a retired household’s tax bill each year, taken together rather than one at a time: how much to convert to Roth and in which years; which account to spend from and in what order; when to claim Social Security; how to keep Medicare premiums from stepping up; how to realize capital gains, or avoid them; what required distributions will force at 73 or 75 and what to do about it beforehand; and how the estate plan changes the answer. Then a return that reflects all of it.

For a household with $2 million to $5 million saved, most of it tax-deferred, these decisions routinely move six figures of lifetime tax. They also interact: a conversion that fills the 24% bracket can cost a Medicare tier two years later; a large gain harvested in the wrong year can pull Social Security benefits into income. Planning them separately is how households pay for the same dollar twice.

The seven decisions

What gets decided, and where to read more

Each guide below works through one decision with the 2026 figures and the primary sources they come from. The planning relationship is where they are decided together.

How much to convert to Roth, and when

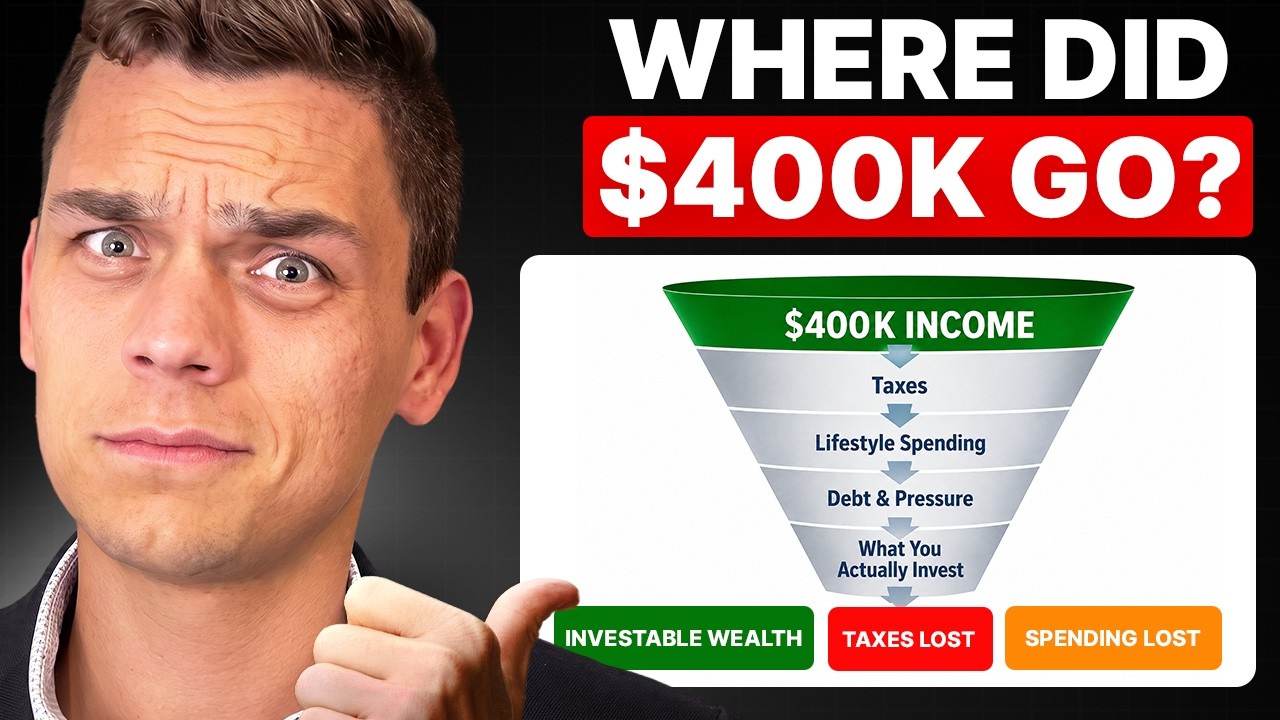
Conversions move tax from a later year to this one. The work is comparing the rate you would pay now, all in, against the rates you, a surviving spouse or your heirs would otherwise pay, and pacing the conversions slice by slice against the brackets and the Medicare tiers.
Read the guide

Medicare premiums set by your tax return

Above $218,000 of joint income, Part B and Part D premiums step up in tiers, set from the return two years earlier. Every conversion, gain and distribution is planned against those thresholds.

Read the guide

Required minimum distributions at 73 or 75

Distributions become mandatory at 73 for people born 1951 through 1959 and 75 for those born in 1960 or later. The balance on that day, and the income it forces, is what the years before it are for. Charitable households can route up to $111,000 a year of it to charity tax-free.

Read the guide

Which account funds which year

Taxable, tax-deferred and Roth money each cost something different to spend. The order you draw from them, and how that order changes once Social Security and required distributions arrive, decides how much of a portfolio you keep.

Read the guide

Which investments belong in which account

Bonds, stock funds and the assets you intend to leave to heirs are taxed differently depending on where they sit. Asset location is the part of portfolio design that changes the after-tax result without changing the risk.

Read the guide

Capital gains, realized on purpose

Long-term gains have their own 0%, 15% and 20% schedule plus the 3.8% investment tax, and they compete with Roth conversions for the same bracket room. Gains are timed, harvested and given away with the whole return in view.

Read the guide

When to claim Social Security, and what it costs in tax

Delaying to 70 raises the benefit 8% a year; up to 85% of it is then taxable, and the years before claiming are the natural window for conversions. Timing is decided alongside the rest of the income plan, not on its own.

Read the guide

Why the fee matters here

Retirement Tax Advice Is Where a Percentage Fee Pulls Hardest

Nearly every recommendation in retirement tax planning reduces the assets an advisor manages. Paying conversion tax from the portfolio, spending down an IRA before Social Security, giving appreciated stock to charity, paying off a mortgage, buying a pension-like annuity: each is sometimes right, and each shrinks the base a percentage fee is charged on. An advisor charging 1% on $3 million earns $30,000 a year and less after every one of those moves.

A flat fee removes that pull. It does not make the advice correct by itself, but it means the recommendation does not change what the advisor is paid. How that plays out on conversions in particular is set out in Roth conversions and the AUM fee; the dollar difference over a retirement is on the flat fee vs AUM calculator.

What is included

Two memberships, one relationship

Both include a dedicated Flames advisor, comprehensive planning, investment management and the Financial Dashboard. Premier adds the modeling, implementation and filing that a retirement tax plan needs. Full scope and eligibility are on the pricing page.

Comprehensive planning

Flames Planning

$900 / quarter

Billed quarterly in advance · $3,600 annualized

A dedicated advisor coordinating the whole picture, with tax guidance running through it rather than bolted on at the end.

What it covers

  • Investments, taxes, retirement, insurance and estate decisions coordinated in one plan
  • Personalized investment management, monitoring and rebalancing
  • Proactive tax-planning guidance and a planning-focused review of one completed personal tax return each year
  • Day-one access to Wealth.com estate documents
  • Ongoing planning conversations, plan updates and Dashboard updates
Planning details
Advanced planning and filing

Flames Premier

$1,650 / quarter

Billed quarterly in advance · $6,600 annualized

Everything in Flames Planning, plus the modeling, implementation and filing a retirement tax plan needs.

What it adds

  • Ongoing tax projections, Roth-conversion and capital-gain modeling
  • Retirement-income, Social Security and withdrawal implementation
  • Eligible tax-return preparation and filing through an independent tax partner, joining by September 30 of the tax year
  • Equity-compensation, concentrated-position and charitable planning
  • Advanced estate strategy with attorney coordination
Premier details

How the first year runs

A discovery meeting, then a full picture of accounts, income sources and the current return. From there: a multi-year projection, a conversion and withdrawal schedule for the current year, Medicare and Social Security timing, and the estate documents brought into line with the plan. The plan is revisited every year as the figures change, because they do. How the relationship works.

Your state changes the math

The same conversion costs a different amount by state

State tax is part of the rate on every conversion and withdrawal. Each state page sets out how the state taxes income, retirement income and estates, with the source beside each figure.

Minnesota

Retirement income taxed at up to 9.85%, Social Security only partly sheltered, and an estate tax from $3 million. The state where the planning is worth the most.

State page

Illinois and Pennsylvania

Both leave retirement income untaxed, and neither taxes a Roth conversion done properly, so the conversion decision is federal-only. Pennsylvania adds an inheritance tax to plan around.

State page

Texas, Florida and other no-income-tax states

No state layer at all. Households arriving from a taxing state plan around the state they left, and use the low-tax years for conversions.

State page

Every state and city we serve

The full list, with the tax layer for each state and what is local to each city.

All states and cities

Comparing firms

Weighing Flames FP against a subscription firm?

Many households arrive here comparing flat-fee firms. The side-by-side pages use each firm’s published pricing and scope, with the date they were checked.

Flames FP vs Facet

Membership pricing, who you meet with, what tax work is included, and how each handles Roth-conversion and retirement-income planning.

Facet comparison

Flames FP vs Range

Team model against a dedicated advisor, and what each membership tier covers.

Range comparison

Four flat-fee options in one table

Facet alternatives for 2026, with published membership details and the date they were checked.

Facet alternatives

Common questions

Retirement Tax Planning Questions

What does retirement tax planning at Flames FP include?

Coordinating the decisions that set a retired household's tax bill each year: how much to convert to Roth and when, which account to spend from, when to claim Social Security, how to keep Medicare premiums in check, how to manage capital gains and required distributions, and how the estate plan fits. Planning members receive proactive tax guidance and a planning-focused review of a completed personal return; Premier members add ongoing tax projections, Roth-conversion and capital-gain modeling, retirement-income and withdrawal implementation, and eligible tax-return preparation and filing through an independent tax partner.

Do you prepare and file tax returns?

For eligible Premier members, yes: one federal individual return and the required state returns are prepared and filed under a separate engagement with Flames FP's designated independent tax partner, with Flames providing the planning and coordination. To qualify, a client joins Premier by September 30 of the tax year and remains a member through filing. Planning includes a review of a completed return rather than preparation.

How is this different from tax planning at an advisor who charges on assets?

The advice is meant to be the same; the incentives are not. Paying conversion tax from a portfolio, spending down an IRA, buying an annuity or paying off a mortgage all shrink the assets a percentage fee is charged on. Flames FP charges a flat quarterly membership, so the recommendation does not change the fee either way.

Who is this for?

Most often households with roughly $2 million to $5 million saved, much of it in tax-deferred accounts, who are within about ten years of retiring or have recently retired. The common thread is that the decisions interact and a percentage-of-assets fee has become expensive relative to the work.

Does it matter which state I live in?

Yes. State tax is part of the rate on every conversion and withdrawal, and states differ sharply: Minnesota taxes retirement income at up to 9.85%, Illinois, Pennsylvania and Iowa (for those 55 and older) exempt it, and Texas and Florida have no income tax. Flames FP is based in Minnetonka, Minnesota and works with clients virtually nationwide where permitted; each state page sets out the rules with sources.

What does it cost?

Flames Planning is $900 per quarter ($3,600 a year) and Flames Premier is $1,650 per quarter ($6,600 a year), billed quarterly in advance with no annual commitment, no setup fee and no fee on assets.

Next step

Bring the return, the statements and the questions.

A discovery meeting covers where you are, what you pay for advice today in dollars, and whether a fixed quarterly membership fits the work ahead.